Market overview and structural significance of the Sand Control Services Market
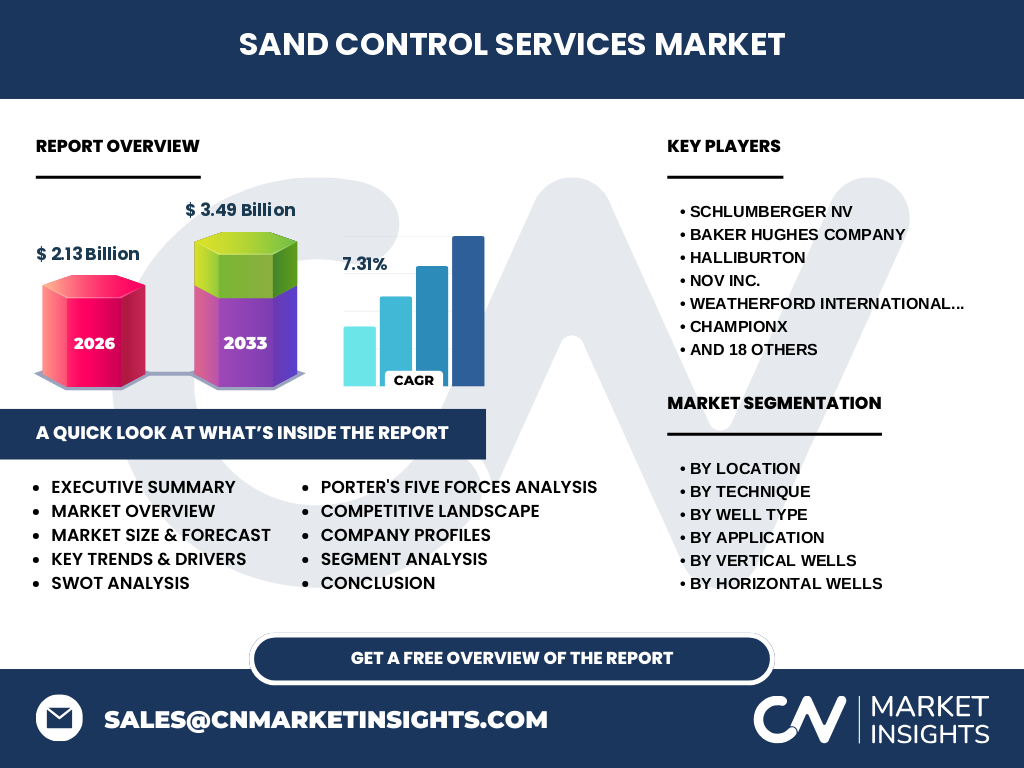
Our analysis indicates that the Sand Control Services Market is valued at 2.13 Billion in 2026, serving as a critical upstream segment for mitigating formation sand production in unconsolidated reservoirs. Utilizing specialized raw materials like high-grade bauxite and resin-coated gravel, industry participants protect critical subsea and surface infrastructure from abrasive erosion, ensuring uninterrupted hydrocarbon flow across complex geological formations.
Structural Growth Drivers and Market Restraints
The market is propelled by rising drilling densities in fragile, poorly consolidated offshore formations, which demand advanced Gravel Pack and Frac Pack interventions. However, severe regulatory compliance imposed by agencies like the Bureau of Safety and Environmental Enforcement (BSEE) alongside volatile raw material supply chains acts as a notable operational restraint for service providers.
Emerging Industry Trends in Sand Control Services
The shift toward complex horizontal drilling has accelerated the deployment of proprietary Sand Screens and inflow control devices. Industry innovators are integrating real-time downhole telemetry to optimize gravel placement, minimizing skin damage and maximizing hydrocarbon recovery rates in highly deviated multilateral wellbores.
COVID-19 Impact Analysis and Post-Pandemic Recovery
Pandemic-induced capital expenditure freezes drastically curtailed completion activity, yet aggressive upstream recovery strategies have successfully rebounded the sector toward its 7.31% CAGR trajectory. Supply chain bottlenecks at major logistics hubs temporarily inflated raw material costs, forcing operators to fast-track digital automation and remote operational monitoring.
Competitive Benchmarking and Market Concentration
The competitive landscape features dominant oilfield service titans such as Schlumberger NV, Baker Hughes Company, and Halliburton, who leverage extensive global footprints to dominate offshore tenders. Meanwhile, specialized regional players like Tendeka and TAM International Inc. carve out high-margin niches through proprietary mechanical isolation and inflow control technologies.
Executive Summary: Navigating the Sand Control Services Market
Driven by deepwater developments and complex horizontal well architectures, the Sand Control Services Market is positioned for robust expansion. Our research projects total market valuation to surge from 2.13 Billion in 2026 to reach 3.49 Billion by 2033, underscoring compelling investment opportunities in advanced completion technologies.
Market Forecast and Valuation Trajectory (2027-2033)
Based on our econometric models, the market will expand steadily at a compound annual growth rate of 7.31% through the forecast period. This steady upward trajectory from 2027 to 2033 is underwritten by sustained investments in deepwater offshore assets and enhanced oil recovery projects across mature basins.
Comprehensive Segmentation Analysis
The market is segmented by location into onshore and offshore environments; by technique encompassing gravel pack, frac pack, sand screens, and resin-coated gravel; and by well type covering horizontal (multilateral, extended reach, offshore) and vertical (conventional, deviated) configurations. Application domains are further divided into cased hole and open hole environments, each dictating specific downhole chemical and mechanical requirements.
Geographic Distribution and Regional Performance
Regional performance highlights strong offshore activity across the Gulf of Mexico and the North Sea, while onshore Middle Eastern basins drive massive volume demand for resin-coated gravel applications. Logistical hubs near major port cities facilitate rapid deployment of specialized completion equipment to active drilling rigs.
In-Depth Regional Market Review
North America remains a high-value adopter of advanced frac pack technologies, supported by active participation from regional experts like Nine Energy Service Inc. and Expro Group. Concurrently, the Middle East showcases sustained high-volume demand in conventional vertical assets, backed by localized operational infrastructure.
Strategic Company Profiles in the Sand Control Sector
Industry leaders like Weatherford International Plc, NOV Inc., and ChampionX maintain competitive moats through continuous R&D investment in corrosion-resistant sand screens and chemical consolidants. Strategic acquisitions of boutique technology firms allow these heavyweights to offer integrated, turn-key sand management solutions to major operators.
Porter's Five Forces Industry Assessment
Bargaining power of buyers remains moderate-to-high due to consolidated oil and gas operator spending discipline, while supplier power is constrained by specialized raw material availability. Threat of substitution is low given the irreplaceable physical necessity of sand exclusion in unconsolidated formations, though rivalry among top-tier service providers is fierce.
SWOT Analysis of the Sand Control Services Industry
Key strengths lie in advanced metallurgical screen designs and high-reliability pumping spreads, while weaknesses involve high capital expenditures for offshore deployment. Opportunities abound in expanding extended-reach horizontal wells, with threats centered around accelerated global energy transition mandates impacting long-term upstream budgets.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material extraction, including industrial quartz sand, bauxite, and specialized polymers, processed by chemical manufacturers before reaching service providers. These tier-one contractors integrate the materials into physical downhole tools and pumping services deployed directly for upstream exploration and production companies.
Investment Insights and High-Potential Growth Areas
High-potential capital allocation targets automated downhole sand monitoring tools and environmentally sustainable resin-coated gravel formulations. Investors should prioritize asset-light technology providers partnering with major oilfield contractors to capture upside in the expanding offshore horizontal completion segment.
Conclusion and Strategic Takeaways
Reaching 3.49 Billion by 2033, the Sand Control Services Market rewards technological differentiation and operational safety compliance. Companies mastering proprietary screen metallurgy and real-time wellbore telemetry will capture outsized market share.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by synthesizing primary stakeholder interviews with C-level upstream executives, secondary macroeconomic indicators, and official trade registry data from international energy bureaus. Bottom-up revenue aggregation of key market participants ensures high statistical confidence in our financial models.
Scope of the Report and Coverage Parameters
This report encompasses comprehensive global analysis of the Sand Control Services Market across all specified geographical regions, well configurations, and technological classifications from 2026 through 2033. Excluded from this scope are localized, unmetered artisanal extraction operations and domestic intrastate sand mining unassociated with engineered well completions.
Recent Corporate Developments and Strategic Alliances
Recent market dynamism features strategic joint ventures and product launches aimed at lowering carbon footprints during hydraulic fracturing and gravel packing operations. Firms like Superior Energy Services Inc. and Welltec A S have recently introduced deployment systems that minimize vessel time and reduce emissions during offshore interventions.